VA home loan guidance for veterans, active duty service members, Guard and Reserve members and surviving spouses.
Every service history comes with its own questions. Find yours, then let’s talk through what your VA home loan benefit can do for you.
New orders, a new duty station and a move date that is not always yours to set.
Drill weekends, deployments and a civilian career, all part of one picture.
Understanding the home loan benefit that may be available to you and your family.
Active duty, separation, Guard time or a mix of all three? We start with your Certificate of Eligibility and the bigger picture.
How your time in uniform shapes your eligibility and entitlement.
The home, the location and the payment that fit your next chapter.
What is worth exploring from here, at a pace that suits you.
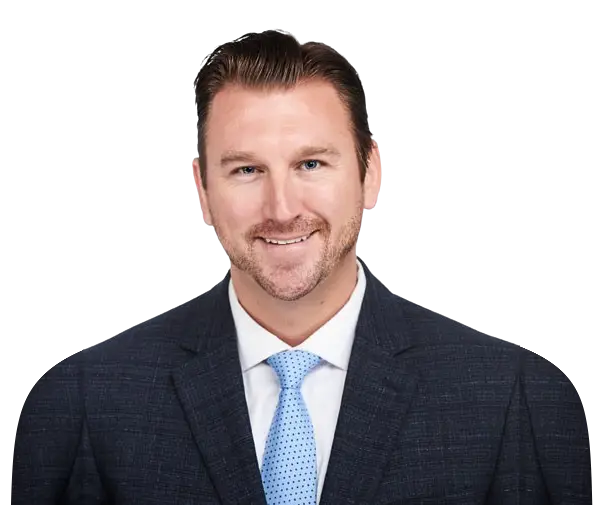
I'm a mortgage loan officer focused on VA home loans, helping veterans, service members and military families understand the benefit they earned and use it with confidence.
Before home lending, I passed the Series 7 and Series 66 exams as a financial advisor. I graduated with honors from Cal State Fullerton in Business Administration, with an emphasis in Finance and Marketing.
Kevin Fyfe · NMLS #1055035
Introduction video to be added
Tell me what you’re curious about, even if your move is a year away.
We request your Certificate of Eligibility and review your entitlement together.
Get clear on what makes sense for you and your family.
4.9 average from 100 client reviews on Experience.com and Zillow
A few questions veterans and service members ask first.
Yes. Many of my conversations start months before a move. Early questions make the whole process calmer later.
Often, no. Eligible borrowers with full entitlement can buy with no down payment, subject to credit, income and lender requirements.
No. VA loans do not require monthly mortgage insurance. Most borrowers pay a VA funding fee, which can usually be financed, and veterans receiving VA disability compensation are generally exempt.
Yes. The benefit is reusable, and depending on your remaining entitlement you may be able to buy again while you still own a home.
Just your questions. A DD214 or statement of service helps, and we can request your Certificate of Eligibility together.
A quick look at a monthly VA home loan payment, with no monthly mortgage insurance and the funding fee built in.
Estimated monthly payment
$0/mo
Estimate only, not a loan offer. Your rate, payment and funding fee depend on your eligibility, credit and lender requirements.
A VA loan question is enough to get started.